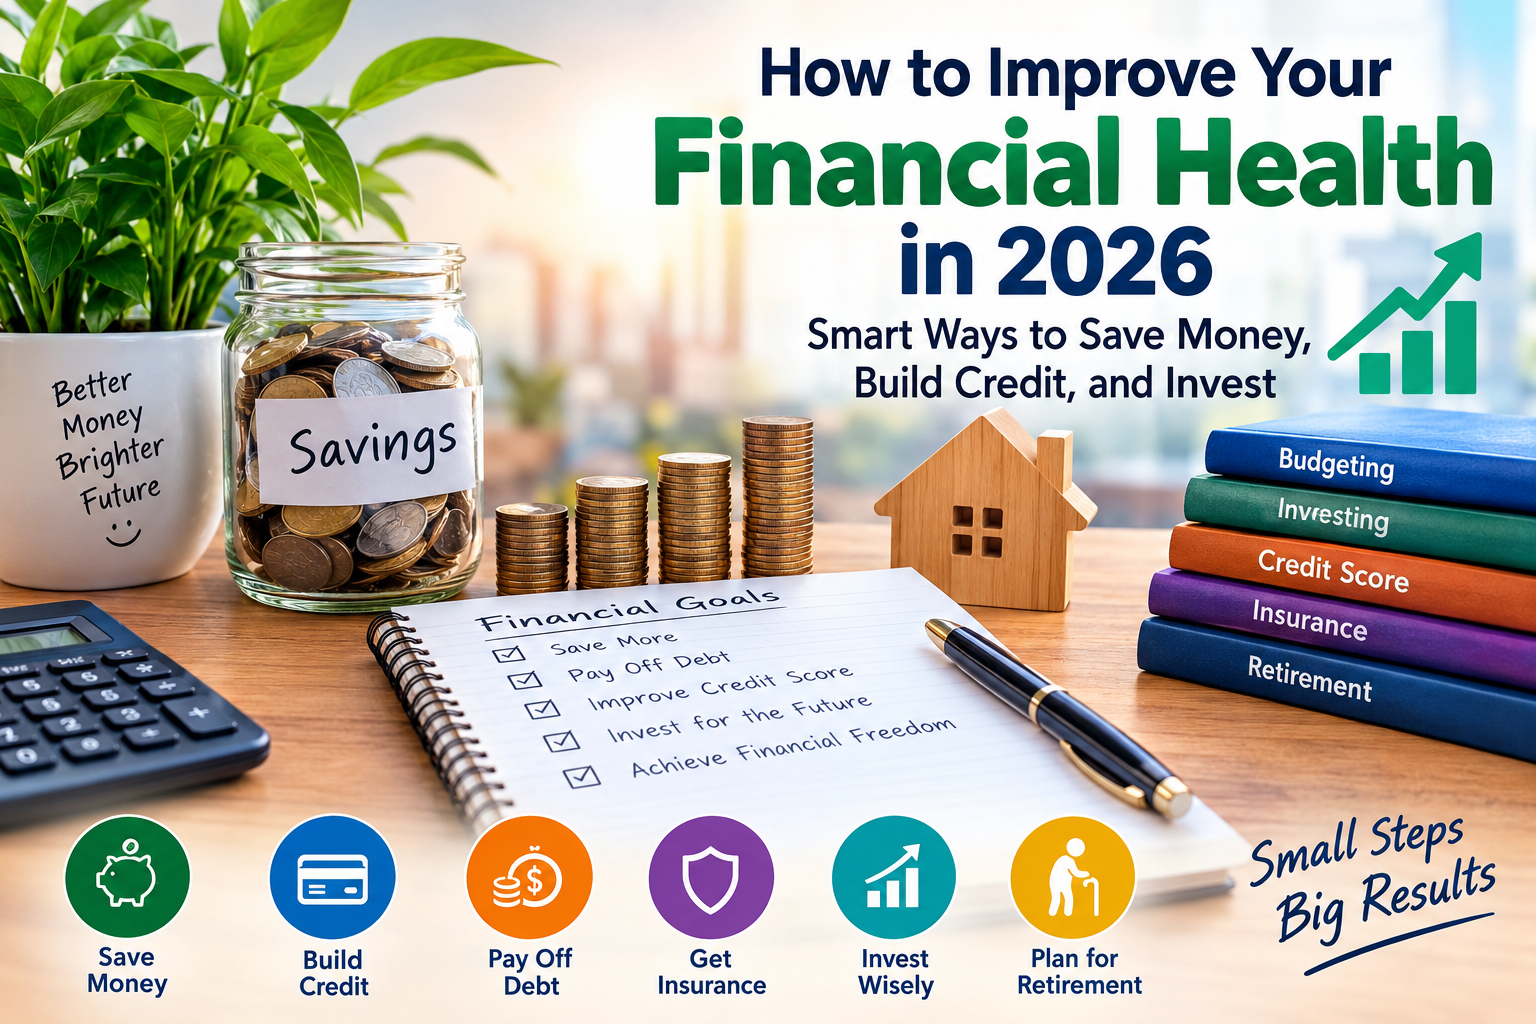
Financial health has become more important than ever. Rising living costs, changing interest rates, unexpected expenses, and the growing cost of everyday services make it essential to manage money carefully. Whether you are trying to save more, improve your credit score, reduce debt, or start investing, small financial decisions can make a major difference over time.
The good news is that improving your financial situation does not always require a high income. With proper budgeting, responsible borrowing, and smart financial planning, you can gradually build a stronger financial future.
1. Create a Realistic Monthly Budget
The first step toward better financial health is understanding where your money goes.
A monthly budget helps you track your income and divide it between essential expenses, savings, debt payments, and personal spending. Start by listing your monthly income and then record expenses such as rent or mortgage payments, utilities, groceries, transportation, insurance, subscriptions, and entertainment.
A simple budgeting system can divide your income into three categories:
- Essential expenses
- Financial goals
- Personal spending
The exact percentages depend on your situation, but the goal should be to make sure your spending does not consistently exceed your income.
Tracking expenses can also reveal unnecessary subscriptions and purchases that quietly consume money every month.
2. Build an Emergency Fund
Unexpected expenses can quickly create financial stress. Car repairs, medical bills, job interruptions, or urgent home expenses can happen without warning.
An emergency fund provides a financial safety net.
A common goal is to eventually save between three and six months of essential living expenses. However, you do not need to reach that amount immediately.
Start with a smaller target, such as $500 or $1,000, and gradually increase it. Keeping emergency savings in an accessible savings account can help you avoid relying on expensive credit cards or high-interest loans when something unexpected happens.
Automatic transfers can make saving easier because a fixed amount moves into savings every payday.
3. Improve Your Credit Score
Your credit score can influence the cost of borrowing money. Lenders may use credit information when evaluating applications for credit cards, personal loans, auto financing, and mortgages.
A stronger credit profile may help you qualify for better borrowing terms.
Some important habits include:
- Paying bills on time
- Keeping credit card balances under control
- Avoiding unnecessary applications for new credit
- Reviewing credit reports for inaccurate information
- Maintaining older credit accounts when appropriate
Payment history is particularly important. Even a single missed payment can potentially affect your credit profile, depending on the circumstances and reporting rules.
Checking your credit reports periodically can also help you identify accounts or information that you do not recognize.
4. Pay Down High-Interest Debt
High-interest debt can make it difficult to build wealth because a significant portion of your monthly payment may go toward interest.
Credit card balances are a common example.
One strategy is the debt avalanche method, where you focus on paying the highest-interest debt first while making minimum payments on other debts.
Another approach is the debt snowball method, where you pay off the smallest balance first to create momentum.
The best method depends on your financial situation and personality. What matters most is creating a consistent repayment plan and avoiding additional unnecessary debt.
Before taking a new personal loan or balance-transfer product, carefully compare the annual percentage rate, fees, repayment period, and total cost.
5. Compare Insurance Before Buying
Insurance is another major part of financial planning. Depending on your situation, you may need health insurance, auto insurance, homeowners or renters insurance, life insurance, or other coverage.
However, paying for insurance does not mean you should automatically accept the first quote you receive.
Comparing policies can help you understand differences in premiums, deductibles, coverage limits, exclusions, and additional benefits.
A cheaper policy is not necessarily the best policy. The right choice should provide appropriate protection while remaining affordable within your budget.
Reviewing your insurance coverage periodically is also useful because your needs can change after moving, purchasing a vehicle, changing jobs, getting married, or making other major life decisions.
6. Start Investing for the Long Term
Saving protects your money, while investing can potentially help it grow over the long term.
Many people delay investing because they believe they need a large amount of money to get started. In reality, some investment platforms allow people to begin with relatively small amounts.
Common investment categories include:
- Stocks
- Bonds
- Mutual funds
- Exchange-traded funds
- Retirement accounts
- Real estate
Every investment involves some level of risk. Higher potential returns generally come with greater volatility.
For long-term investors, diversification can help reduce the impact of one investment performing poorly. Instead of putting all your money into a single company or asset, diversification spreads exposure across different investments.
Before investing, understand your time horizon, risk tolerance, fees, and financial goals.
7. Take Advantage of Retirement Accounts
Retirement planning is easier when you start early because compound growth can work over many years.
Depending on your country and employment situation, retirement accounts may provide tax advantages or employer contributions.
If your employer offers a retirement plan with matching contributions, understand the rules and consider contributing enough to receive available matching benefits when appropriate.
The important lesson is simple: retirement planning should not be something you postpone indefinitely.
Even relatively small contributions made consistently over a long period can become meaningful because of compound growth.
8. Be Careful With Loans
Loans can be useful for major purchases, education, business expenses, or emergencies, but borrowing comes with a cost.
Before accepting a loan, look beyond the monthly payment.
Consider:
- Interest rate
- Annual percentage rate
- Origination fees
- Late-payment charges
- Repayment period
- Total amount repaid
A loan with a low monthly payment may still be expensive if the repayment period is very long.
Always compare multiple offers when possible and make sure the payment fits comfortably within your budget.
9. Reduce Unnecessary Monthly Expenses
Increasing income is one way to improve your financial situation, but reducing unnecessary expenses can have an immediate effect.
Review recurring payments such as streaming services, memberships, mobile plans, software subscriptions, and other automatic charges.
You may discover services that you rarely use.
You can also compare prices for internet, insurance, utilities, and other services when contracts or promotional periods end.
Saving $50 or $100 each month may seem small, but consistent savings can become significant over several years.
10. Protect Yourself From Financial Scams
As digital banking and online payments become more common, financial scams have also become increasingly sophisticated.
Never share passwords, security codes, banking credentials, or sensitive financial information with someone who contacts you unexpectedly.
Be cautious of messages claiming that you have won money, owe an urgent payment, or must provide personal information immediately.
Scammers often create a sense of urgency to prevent people from thinking carefully.
If something seems suspicious, contact the financial institution or company through an official website or verified phone number instead of using contact information provided in a suspicious message.
11. Increase Your Financial Knowledge
Financial education can be one of the most valuable investments you make.
Learn how interest rates work, how credit scores are calculated, how loans are priced, how insurance works, and how different investment products operate.
Understanding basic financial concepts can help you make better decisions and avoid expensive mistakes.
You do not need to become a professional investor or financial expert. Even learning one useful concept each week can significantly improve your financial knowledge over time.
12. Create a Long-Term Financial Plan
A strong financial future usually comes from consistent decisions rather than one major action.
Set short-term goals such as paying a credit card balance or building an emergency fund.
Then create medium- and long-term goals, such as purchasing a home, starting a business, funding education, or preparing for retirement.
Write down your goals and give each one a target amount and deadline.
Review your progress regularly and adjust your plan when your income, expenses, or priorities change.
Final Thoughts
Improving your financial health is a gradual process. You do not need to become wealthy overnight or completely change your lifestyle in one day.
Start by creating a realistic budget, building emergency savings, reducing high-interest debt, improving your credit habits, reviewing insurance coverage, and learning about long-term investing.
The most important factor is consistency.
Small financial improvements made today can create much bigger benefits in the future. By making informed decisions and regularly reviewing your financial goals, you can build greater financial stability and become better prepared for unexpected expenses and future opportunities.
Disclaimer: This article is for general educational purposes only and should not be considered personalized financial, investment, tax, insurance, or legal advice. Financial products and regulations vary by location, so consider consulting a qualified professional before making major financial decisions.